
New Compliance Obligations and Simplified Rules for International Holding Companies
For fiscal periods beginning on or after 1 January 2027, certain Panamanian entities will be required to demonstrate adequate economic substance to preserve the existing tax treatment of their foreign-source passive income.
Following our previous communication on Law 526 of 28 May 2026, Executive Decree No. 32 of 2 September 2026 has provided further guidance on how companies must demonstrate compliance with the new requirements.
While the regulations introduce additional obligations concerning local presence, management and documentation, they also establish a simplified economic substance regime for qualifying pure holding companies, which may be particularly relevant for international corporate and wealth-holding structures.
Which Entities Are Affected?
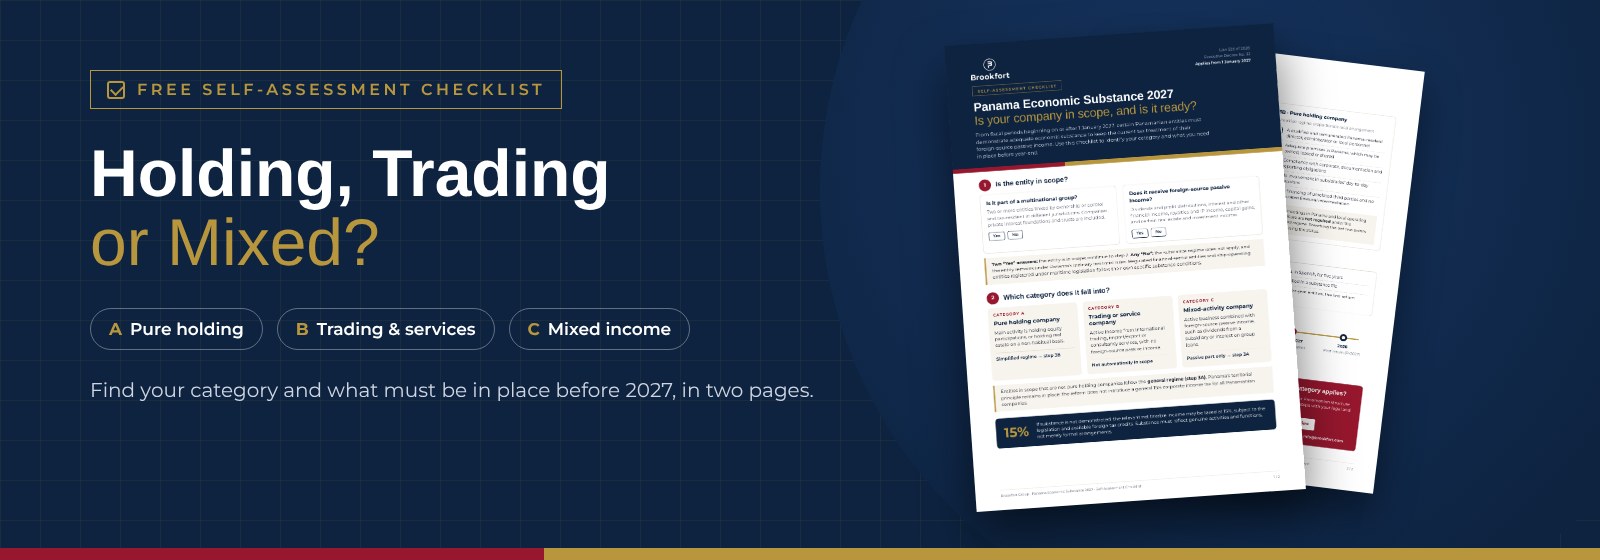
The new regime applies to entities incorporated or domiciled in Panama, including companies, private interest foundations and trusts, that form part of a multinational group and receive certain categories of foreign-source passive income. A multinational group means two or more entities linked by ownership or control and tax-resident in different jurisdictions. Covered income includes:
- Dividends and profit distributions.
- Interest and other financial income.
- Royalties and intellectual property income.
- Capital gains.
- Certain real estate and investment income.
Failure to satisfy the applicable economic substance requirements may result in a 15% tax on the relevant net taxable income, subject to the provisions of the legislation, including available foreign tax credits.
Importantly, the new rules do not introduce a general 15% corporate income tax for all Panamanian companies. Panama’s territorial taxation principle remains in place.
Regulated financial sector entities and ship-operating entities registered under Panama’s maritime legislation are subject to their own specific substance conditions.
Simplified Requirements for Pure Holding Companies in Panama
One of the most significant developments is the introduction of a simplified regime for qualifying entities whose main activity is holding equity participations or holding real estate on a non-habitual basis.
Under this regime, economic substance may be demonstrated through a proportionate local arrangement involving:
- A suitably qualified and remunerated Panama-resident director or administrator, or appropriate local personnel.
- Adequate premises in Panama, which may be owned, leased or shared.
- Compliance with applicable corporate, documentation and reporting obligations.
Qualifying pure holding companies are not required to hold board meetings in Panama or to incur local operating expenditure, two of the main requirements under the general regime.
This may allow international holding structures to maintain an efficient presence in Panama without establishing a fully operational local organization.
However, eligibility must be assessed individually. A holding company loses this status if it becomes actively involved in the day-to-day decisions of its subsidiaries, finances unrelated third parties or carries out regulated financial intermediation.
What About Trading and Service Companies?
Active business income, including income from international trading and certain service activities, does not fall within the new economic substance regime merely because it is earned by a Panamanian company.
Accordingly, Panamanian entities engaged in international trading, import/export activities or consultancy services are not automatically subject to these additional requirements.
Their tax treatment nevertheless continues to depend on Panama’s ordinary territorial source rules and the specific circumstances of their operations.
What About Mixed-Activity Companies?
Companies combining active business activities with foreign-source passive income may be subject to the new requirements in respect of the passive income component.
What Should Companies Do Before 2027?
With the new regime approaching, companies potentially affected should review their existing structures before the end of 2026. Particular attention should be given to:
Determining whether the entity belongs to a multinational group and receives relevant foreign-source passive income.
Assessing eligibility for the simplified economic substance regime.
Reviewing existing directors, personnel, office arrangements and service providers.
Establishing appropriate management procedures and, for entities under the general regime, holding at least two in-person board meetings a year in Panama, with strategic decisions properly minuted.
Preparing the necessary corporate records, agreements and expenditure documentation, to be kept in Panama, in Spanish, for five years. Substance information is reported in the annual income tax return; for calendar-year entities, the first return affected is the one for fiscal year 2027, filed in 2028.
For entities subject to the general regime, the regulations require particular attention to strategic decision-making, local resources and the effective performance of relevant activities in Panama. Core activities may be outsourced only if they are performed in Panama under a written agreement with appropriate monitoring.
Companies should begin preparing before 1 January 2027, as economic substance must reflect genuine activities and functions rather than merely formal arrangements.
HOW CAN BROOKFORT ASSIST?
Brookfort Group provides international fiduciary, corporate and administrative services, including solutions for holding companies and other entities established in Panama.
We can assist directly or in coordination with qualified local professionals through:
- Initial corporate structure reviews and coordination of economic substance assessments.
- Professional director and corporate administration services.
- Registered office and coordination of local premises.
- Organization of board meetings and maintenance of corporate records.
- Coordination of accounting, tax reporting and regulatory compliance.
- Implementation and ongoing administration of tailored economic substance arrangements.
Our objective is to help clients maintain compliant, efficient and appropriately structured international operations while addressing the practical requirements of the new legislation.
Is Your Panamanian Company Ready for 2027?
With the new requirements approaching, now is the time to assess whether your existing arrangements remain suitable.
Contact Brookfort Group to discuss the implications for your Panamanian entity and explore appropriate corporate administration and economic substance solutions.
Speak with Brookfort